Renewables to exceed 80% of Netherlands' power capacity by 2035, says GlobalData
Grid congestion and negative midday prices shift the Dutch transition from rooftop solar to offshore wind and flexibility.
GlobalData’s latest report, 'Netherlands Power Market Outlook to 2035: Market Trends, Regulations, and Competitive Landscape', provides a comprehensive assessment of the country’s electricity sector. The report analyses installed capacity in GW, electricity generation in TWh, technology mix, and regulatory developments across the historical period from 2020 to 2025 and the forecast period from 2026 to 2035. It also evaluates market drivers, policy frameworks, infrastructure investment, and competitive dynamics using GlobalData’s proprietary databases, primary and secondary research, and in-house analytical expertise.
The Netherlands is recalibrating its power transition as severe transmission constraints and frequent midday negative power prices drive a strategic shift from rooftop solar toward large-scale offshore wind and grid flexibility. As a result, the renewable share of the country’s capacity mix is forecast to increase from 65% to over 80% by 2035.
The country’s cumulative installed power capacity is projected to expand at a compound annual growth rate (CAGR) of 4.0% between 2025 and 2035. Over this period, thermal power’s share is expected to contract by nearly half as coal exits the system.
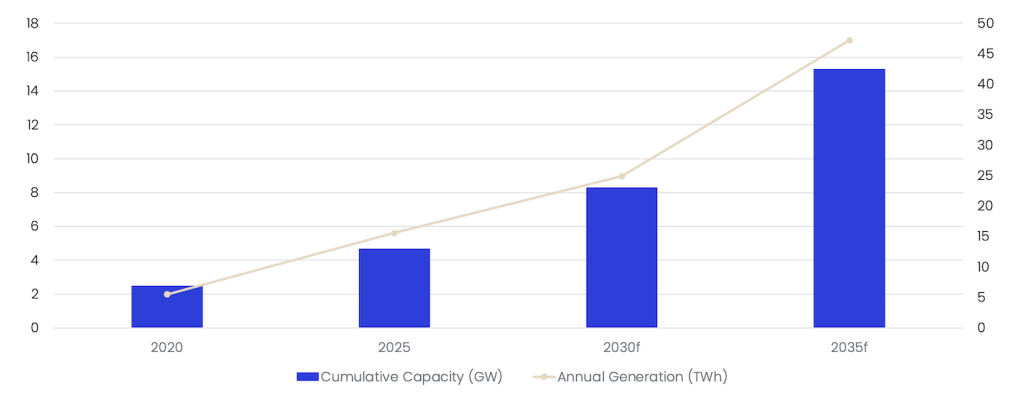
Offshore wind, the Netherlands, capacity (GW) and annual generation (TWh), 2020 – 2035f
Dutch offshore wind capacity is set to more than triple, from 4.7GW in 2025 to 15.3GW by 2035.
The Netherlands achieved one of Europe’s highest per-capita solar adoption rates under generous net-metering rules. However, the widening gap between daytime solar generation peaks and network capacity has created widespread grid connection queues and depressed daytime wholesale prices. In response, policy and commercial momentum is pivoting decisively toward the North Sea, where offshore wind offers higher capacity factors and closer alignment with industrial demand profiles.
Offshore wind is forecast to serve as the principal generation growth engine through 2035, supported by the government’s expanded North Sea roadmaps and restructured tender frameworks. While solar PV continues to represent the single largest share of total installed capacity, annual additions are expected to transition toward utility-scale developments co-located with storage. Gas-fired generation will remain a critical dispatchable backstop, maintaining system stability as coal is completely phased out in accordance with statutory decarbonisation timelines.
Grid congestion is now the central operational challenge across the Dutch electricity system. High-voltage corridors and distribution substations face severe capacity constraints, making network reinforcement, battery energy storage, and industrial demand-side response urgent priorities. The implementation of the Energy Act (Energiewet) establishes an updated regulatory foundation for flexible network access, energy storage deployment, and decentralised trading.
Investment across the Dutch power sector is projected to remain concentrated in offshore wind infrastructure and high-voltage transmission interconnectors, followed by utility-scale solar and battery storage assets. Long-term deployment will be underpinned by the SDE++ incentive regime, evolving contract-for-difference (CfDs) frameworks for offshore sites, and national targets to establish multi-gigawatt green hydrogen electrolyser capacity to absorb surplus renewable generation.
The Netherlands is moving from a volume-led solar expansion toward a more integrated, system-led phase of its energy transition. Delivering on long-term climate targets will depend on synchronising offshore wind commissioning with transmission corridor delivery, expanding electrolyser capacity, and establishing clear market signals for battery storage to relieve pressure on the onshore grid.